For many people, financial success is not measured solely by personal achievements but also by the ability to support family members.
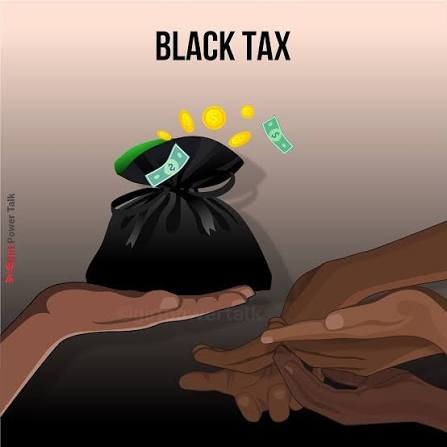
This responsibility, commonly known as “black tax,” refers to the financial assistance provided by working individuals to parents, siblings, extended family, or relatives who depend on them.
Also see: How your emotions are quietly wrecking your finances
Sanlam Financial says, “While helping loved ones can be deeply meaningful and rooted in cultural values, it can also make it difficult to achieve personal financial milestones such as buying a home, building an emergency fund, saving for retirement, or investing for the future. The key is finding a balance that allows you to support your family without compromising your long-term financial well-being.”
Understand your financial position
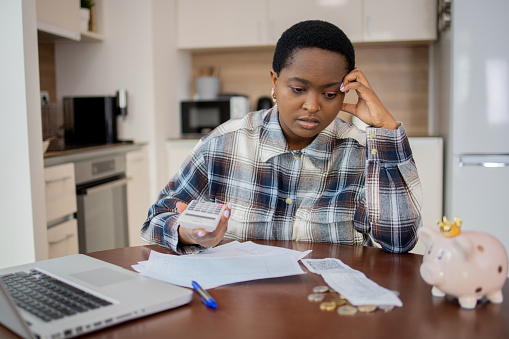
Before committing to regular financial support, take an honest look at your income, expenses, debts, and savings goals. Create a monthly budget that clearly shows how much you can realistically afford to contribute without putting yourself under financial strain.
Knowing your financial limits helps you make informed decisions rather than emotional ones.
Set a fixed support budget
Instead of providing money whenever a request arises, allocate a specific amount each month for family support. Treat this amount as part of your monthly budget.
A fixed budget provides consistency for your family while protecting your own finances from unexpected pressure.
Communicate openly
Money conversations can be uncomfortable, but honesty is essential. If your circumstances change or your financial commitments increase, explain your situation respectfully.
Setting expectations early helps prevent misunderstandings and allows family members to understand what you can realistically contribute.
Prioritise your financial goals
Supporting family should not come at the expense of your financial future. Continue contributing toward important goals such as:
- Building an emergency fund.
- Paying off high-interest debt.
- Saving for retirement.
- Investing for long-term wealth.
- Purchasing a home or funding your children’s education.
Remember that securing your own financial future puts you in a stronger position to help others in the years ahead.
Encourage financial independence
Whenever possible, provide support that encourages long-term stability instead of fostering ongoing dependence. This might include assisting a family member in starting a small business, paying for skills training, or helping them access educational opportunities.
By empowering loved ones to earn their own income, you can alleviate financial pressure on everyone over time.
Also see: The finance propaganda that’s actually good for you
You need to avoid unsustainable debt
It is tempting to borrow money or rely on credit cards to meet family obligations, especially during emergencies. However, accumulating debt to support others can create long-term financial problems for yourself.
If financial assistance requires borrowing beyond your means, it may be time to reassess what you can realistically provide.
Build an emergency fund
Unexpected events such as illness, job loss, or family emergencies can increase requests for financial assistance. Having an emergency fund allows you to respond without disrupting your monthly budget or relying on expensive loans.
Aim to gradually build savings that can cover several months of essential expenses.
Learning to say no when needed
Saying no does not mean you care less about your family. It simply means recognising your financial limits. Declining requests that would jeopardise your own financial stability is a responsible decision.
Where possible, offer alternative forms of support, such as helping relatives find employment opportunities, connecting them with community resources, or assisting with financial planning.
Financial success is not about choosing between family and yourself—it is about creating a sustainable balance that benefits everyone in the long run.
Also see: Money Makeover Tips: How to Save, Invest, and Grow Finances Without Stress
Be the first to know – Join our WhatsApp channel for content worth tapping into. Click here to join!